Monday, August 19, 2013

RENTING vs. BUYING: some of the simple facts revealed!


I hope you found last week’s letter interesting.  If you know someone that could possibly benefit from that information, please feel free to pass it along to them!  This week’s article discusses the pros and cons between renting and buying.  I hope you enjoy it!

RENTING vs. BUYING

We all knew that the recent rock-bottom mortgage rates were too good to last forever, and now they are starting to creep upwards.  While some people may find this upsetting, it should not be viewed as a bad thing—it is quite the opposite!  The slight rise in lending rates means that the government is beginning to release its hold on the lending programs, which means the real estate markets are finally coming back to life!  This is just another sign that our economy is getting stronger.

However great the market has been, the fabled real estate “steals” will not last forever.  The short sales and foreclosures are becoming fewer and farther between, and a $200,000 loan today might not be able to purchase the same home tomorrow…or more realistically, one year from now.  So, if you find yourself straddling that proverbial “to buy or to rent” fence, perhaps you should seriously consider answering that question…today!


To Buy or to Rent:  What Should I Do?

For every advantage, there is a disadvantage, and obviously the opposite is also true.  Let’s take a look at some of the pros and cons of being a homeowner and a tenant.

One of the biggest deterrents to becoming a homeowner is the initial cost of procuring the loan:  the massive down payment typically paid at closing.  Let’s face it, not everybody has several thousand dollars sitting in the bank to chuck down at the closing table.  However, the lenders have realized this and have put together some pretty enticing loan packages to reduce the upfront investment for the buyer.  If you qualify, there are still some tremendous deals lurking around.  A few even offer 100% financing!  Yes, that almost sounds like a car advertisement, but it is true.  203k loans can be 100% financed AND additional money for specific home repairs can be incorporated into the loan, too.  Again, certain qualifying criteria need to be met by the applicant, as well as the house.  Another great loan package is the USDA.  This one is location and income specific to pre-determined areas categorized as rural…and these areas are going to be redrawn later this fall.  The SC Palmetto Heroes loan is a great program for designated individuals who do a great service to our communities and in return receive a smaller pay ratio.  Qualifying individuals include, but are not limited to firefighters, law enforcement officers, teachers, and EMTs.  Finally, there are the VA loans that benefit our active and retired military personnel. 

The SC State Housing Authority has some incredible programs for individuals who qualify.  Their “first-time” home-buyers can receive up to $5000-$8000 in closing fees.  Depending on the specifics of the home and the individual purchasing it, some of these fees will be repaid during the term of the loan and others are actually forgivable!  

Financing aside, let’s look at some more specifics of owning and leasing.  Being a tenant can mean living by someone else’s rules, but it also does have one major freedom:  the ability to move with very few strings attached.  This especially holds true at the end of the lease, when all a tenant stands to lose is a security deposit (unless he was extremely naughty and litigation is needed!).  However, if you intend to stay at least four years in one residence, you can save more money by owning the home.  During this time, you will build equity in the home, which will provide a “cash cushion” between the debt owed and the value of the home.  In addition, your credit can become even better, and, depending on what your accountant does, mortgage interest might be a legitimate tax deduction.  The longer an owner stays in the home, the stronger the equity position becomes.  If he should move after that four year mark and opt not to sell, the home could easily become an investment property that supplements an investment portfolio.  More tax deductions can occur in this situation and sitting down with your tax advisor can help you take advantage of it all!


When renting, one’s expenses are relatively fixed and budget planning can become a much easier task.  However, with no risk, there is no reward!  After all, that IS what an investment is, correct?  You put your money somewhere (hopefully with a calculated risk/gamble) in the hope that it will produce MORE money.  Paying the monthly rent is not an investment.  In the end, you own nothing.  There is equity built, but it is not the renter’s; it is in the homeowner’s pocket.  

It is true that a renter has less work to do in order to maintain the home, which means there is more time to devote to the things that are more fun to do (and less stress!).  However, this, too, comes at a price.  By being a tenant, you must abide by the rules set forth in your lease.  If the rules are broken, generally the penalties are monetary fines.  There may be freedom to move at the end of the lease, but during the duration of the lease term, tenants are generally very limited in what changes they can make to the property, even those that are considered “improvements” in their eyes.  One of the easiest examples of this is painting.  Most rental homes come in very neutral, impersonalized color palettes.  Rental homes leave very little room for individualistic decorating ideas.  

Renters do not receive any tax benefits or advantages.  ‘Nuff said.

Finally, in today’s world the family pet often plays a more important role in the family than pets from a few generations ago.  Today, those pets are seriously considered to be family members.  This holds true in households with and without children.  More often than not, pets come in multiples, and not just in numbers, but in breeds and sizes!  However, homeowners’ insurance companies are taking a stiffer stance when it comes to the faithful family animal.  The aggressive dog breed list is growing by the day and the animals that find themselves on the list are becoming banned from rental properties.  Also, policies that limit the number of cats, or the gender, are becoming quite common.  Finally, the size of the animal is a factor now, too.  At this point in time, the magical number seems to be 30 lbs, but who knows what tomorrow will bring.  Homeowners do not need to worry about these rules and regulations.

Being a homeowner certainly has its positive and negative aspects, as well.  There can be variable costs each month which can make it difficult to plan a budget, since the burden of all repairs generally falls on the homeowner.   However, there will be many months where these costs are low.  The equity in the home will do one of three things at any given time:  it can increase, decrease, or remain the same.  With the strength and health of the market today, the trend in value seems to show that it is finally beginning to increase.   

Besides the large initial investment involved in purchasing a home, the second leading “detrimental” factor is the relocation issue and the prevalent question:  “What if I can’t sell my home?”  The worst case scenario is that you can’t sell your home AND you can’t afford two mortgage payments.  In this situation, you can turn your home into an INVESTMENT home and supplement your retirement securities!  Before getting to that point, though, remember…there were specific reasons that you bought the home, so it will most likely be attractive to someone else!  However, Sarah Turocy, with Sloane Realty, specializes in working with owners and their investment properties.  She can be reached by contacting the Sloane Realty office at (843) 795-4484, or online at www.SloaneTeamRealty.com or email!

The most advantageous aspect of home-ownership is just the plain and simple fact of freedom: the freedom to decorate and remodel at free will!  You do not need permission to paint.  You can create your dream home and live in the pleasure of creating your personal happy space all around you!

Whether or not you live in the home or use it as an investment home, there are wonderful tax advantages that can be utilized.  Your tax adviser can certainly guide you to these benefits.  Remember, the “magic” number to making home ownership work for you is four years.  If you think you will stay put for that length of time, you will save more money if you purchase!

Now, this website isn’t the “end all be all” for definitive mortgage payments, but it can give you a realistic estimate on what your payments could be.  

Check it out—


For more information about the mortgage aspect of the equation, I would suggest contacting Dan Crance with Shelter Mortgage Company.  He can be reached at 843.614.8869 or on the web at www.DanCrance.com

One basic, common necessity of ALL people is to have a place to live, a place to call home.  This is true if you are a tenant OR a homeowner…and it is equally important no matter which category you fall into!  If I can help you at all with any aspect of securing a place to live, let me know; I am excited to help!

Bo Turocy

Broker Associate
Carolina One Real Estate
843.476.9526 (mobile)


Tuesday, August 6, 2013

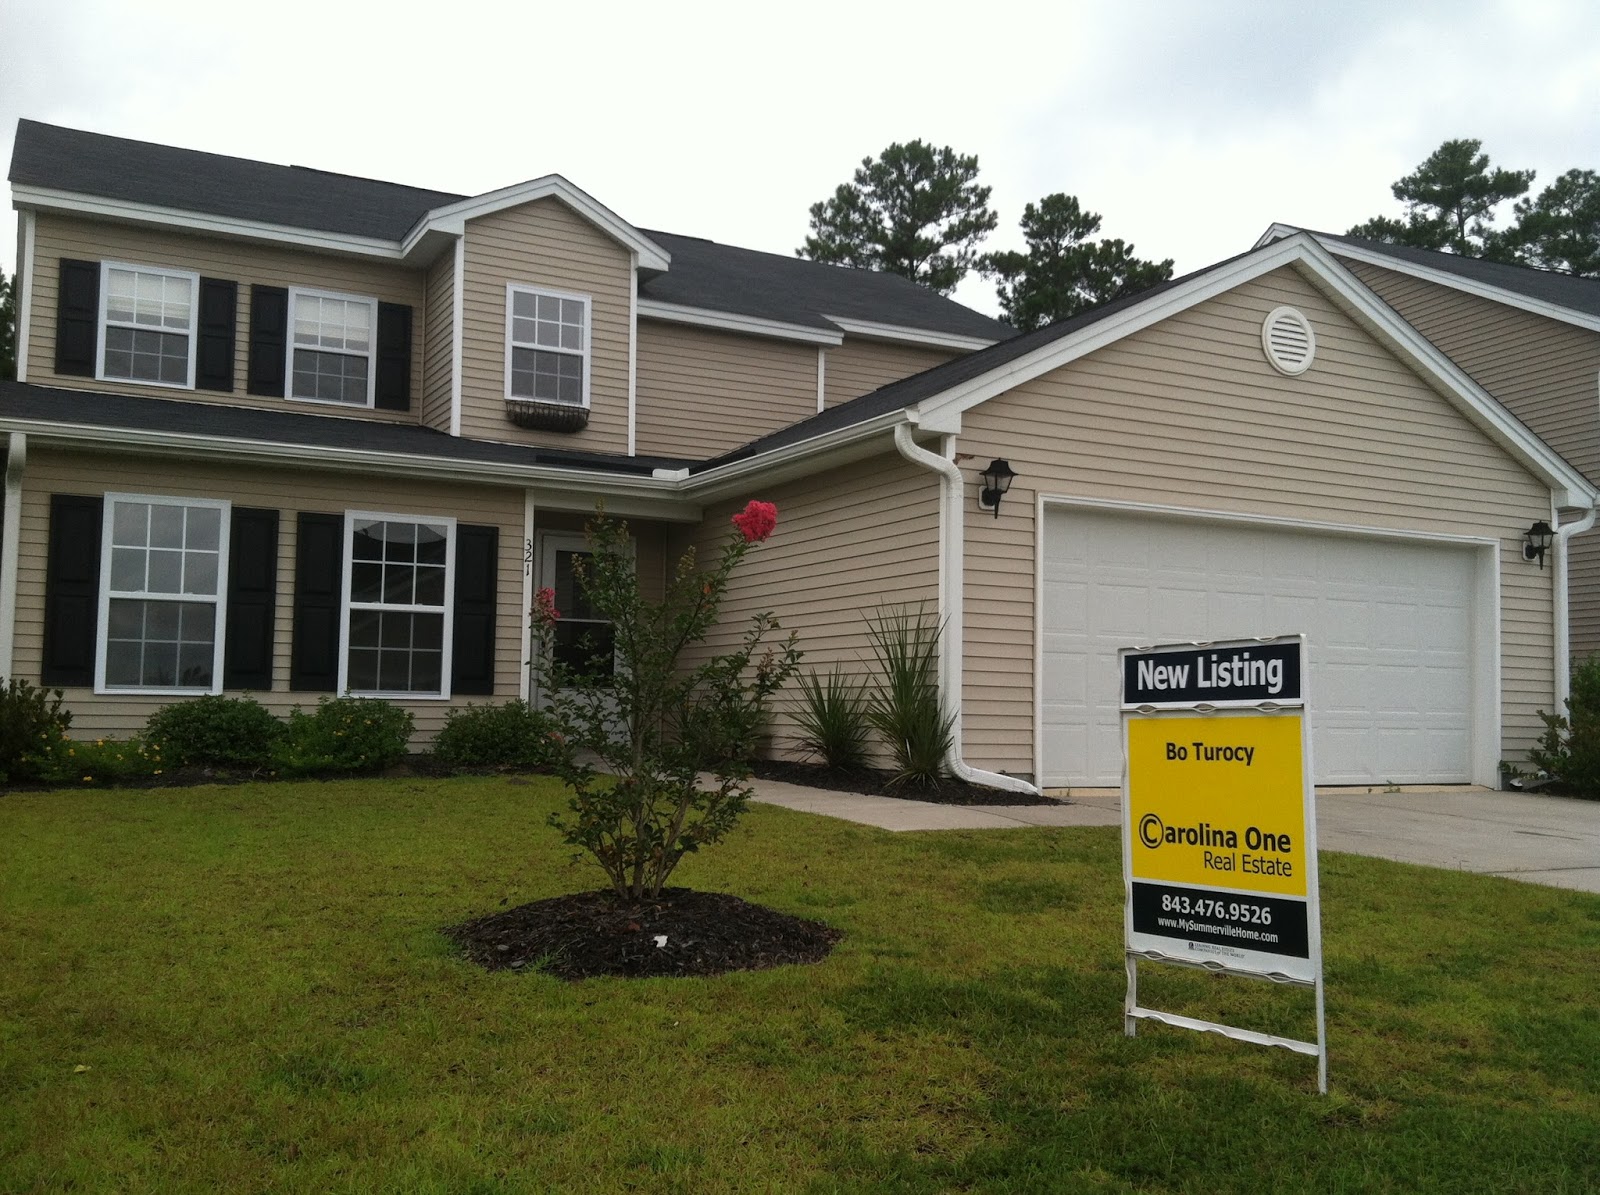
Cane Bay Plantation ~ For Sale~ 321 Deep River Rd.

Welcome back, everyone!  I thought that I would take a break this week from my continuing education series on how to refine your credit and then to determine if buying or renting is the best decision for one's current situation.

This week, I thought I'd focus on a subdivision that is within Summerville, SC:  Cane Bay Plantation.  Now, Cane Bay Plantation has been local, since forever.  Just kidding.  That is the supermarket Piggly Wiggly's marketing catch-phrase!  Cane Bay Plantation has been around since 2007, though.  When it was first developed, the local indigenous population thought it was built on the outskirts of nowhere.  However, in six short years, oh, how that mindset has changed!  

Cane Bay Plantation is 15 minutes from I26 (exit 199) and the plethora of shopping and restaurants at that interchange.  Cane Bay Plantation is 15 minutes from the heart of Goose Creek, SC.  Cane Bay Plantation is 15 minutes from the heart of downtown Moncks Corner.  ...And that is where it sits right now!  As I type and as you read, new construction (both residential AND commercial) are moving towards Cane Bay Plantation!  The Daniel Island Company is currently developing a high-end  community at Carnes Crossroads.  Click here for more information.  Also, MeadWestvaco is developing the Nexton Community, a 4500 acre live-work community that begins at exit 199 and will extend towards Cane Bay Plantation.  Click here for more information about Nexton.  There are also plans in the works within the SC DOT to create another interchange on I26 that will create a new road network to get to highway 176 and...that's right, you guessed it...it will lead one right to Cane Bay Plantation!  The Charleston Post and Courier reports on this project, click here for details.

So, are you getting the picture?  VERY soon, Cane Bay Plantation will be at the heart of everything.  Perhaps in a year or two, Summerville, Goose Creek and Moncks Corner will be saying that they are 15 minutes from Cane Bay Plantation!

So, now that we have arrived at Cane Bay Plantation, what does it have to offer?  Simply answered, "Pretty much everything!"  Cane Bay's developers were forward thinking while in the development stages of planning this community.  Three schools are found within the community itself:  an elementary, middle and high school.  These schools are all new and all beautiful.  I've been inside the high school...it reminded me of a small college.  Talk about preparing your child for the next level!

Within Cane Bay Plantation, you will find a wide variety of subsections, or neighborhoods,  constructed by various prominent builders.  Each subsection is it's own community...some with amenities, some without, some that are established and others that are just in the beginning "infancy"stages of development.

Upon entering Cane Bay Plantation on Cane Bay Blvd., the Old Rice Retreat neighborhood is one of the first communities that you arrive at AND one of the first communities to be built within the subdivision.  Besides being established, this community offers to its residents a community pavilion, swimming pool, and walking/biking paved pathways.  Centex is currently building new homes in the rear of the neighborhood and these home range from the low $170s to the $225k.  They have six different floor plans to choose.  

If new construction isn't your cup of tea...whether it be the  overwhelming stress of dealing with builders and timelines (yes, it can be stressful, especially if you are a first time home buyer!), or perhaps you just do not have the luxury of time, then a resale could be just what you need!  Click here for active listings!

Better yet, don't even bother with the searching...the house you want could be this one:  321 Deep River Road, MLS #1319876.  $215,000  Check out below to learn the details of the home!
Cane Bay Plantation ~ 321 Deep River Road ~ $215,000
AVAILABLE FOR IMMEDIATE OCCUPANCY!! If you have a desire to live in a well sought after community with wonderful, new schools in a GREAT location then look no further. Cane Bay Plantation has made a name for itself because of well-built homes and having some of the best schools in Berkeley county. From nearby walking trails to a refreshing community pool that is literally around the corner, The Old Rice Retreat section of the Cane Bay community has it all. The home at 321 Deep River is subtly large with many individual living spaces that still give the allusion of open spaces. The family can easily gather in the family room, yet still have the feeling of togetherness through the open kitchen while meals are being prepared (did I mention the stainless steel appliances and gas stove?!). Depending on your mood, food can be served in the formal dining room or in the eat-in area for a more simplistic casual experience. A spacious loft can be found at the top of the stairs. This area's uses are endless- it can be utilized as a home office, playroom, reading area with natural lighting, or even a secondary television area. Upstairs also features three large bedrooms (including one of the master bedrooms). The second master bedroom can be found downstairs. Beyond the patio sliding doors is a beautiful pergola. Family get togethers around the grill can be enjoyed here while the large, flat backyard is perfect for activities. Or, perhaps, one could enjoy the quiet solitude of the evening sky sitting when sitting below the pergola decorated with flowers and soft glowing lights. FRESHLY PAINTED AND NEW CARPET THROUGHOUT!! This home has been professionally decorated (the owner is an interior decorator)with conveying custom draperies, designer paint, window treatments and plantation shutters.

If you are interested in either buying, selling or renting (in either a tenant OR a landlord capacity), please contact me today...I can help!  Between my years spent as both a property manager and a real estate agent, I've got you covered.  I would be more than happy to help.

Call (843.476.9526) or email today! 

Monday, July 15, 2013

Good credit, bad credit, no credit, low credit: THE NEVER ENDING TRUTH ABOUT YOUR CREDIT


I hope you found last week’s letter somewhat interesting and informative…after all, housing is a necessity and a lot of thought should be given to it before making a decision that affects your entire household.

Below is some information that discusses credit and proven methods to help rebuild or position your credit in its best possible light.  I hope you find something valuable contained within this blog!

WHAT FACTORS CONTRIBUTE TO YOUR CREDIT SCORE?

Being in real estate, one consistent phrase that is heard a lot, almost too much, from both potential buyers and renters is “…but my credit is not very good.”   Undoubtedly most people have found themselves in difficult situations where tough decisions were made, or perhaps poor choices were made in those younger, pre-adult years.  No matter what led to this point, the important thing is where one goes from here!  Because a credit score is considered low today, there certainly are ways to improve it…it just takes a bit of diligence and time.


First off, let’s take a look at a credit score.  Landlords and mortgage lenders (insurance agencies, potential employers) both use them during the qualifying process, albeit one (the mortgage lender) uses it a bit more heavily.  Obviously, the higher the score equates to a better percentage of paying the loan back (or rent) in a timely, consistent manner.  So, what exactly is this magical number?
Most credit scores range from 250 (extremely low) to 850 (top of the charts).  They are originated by the Fair Isaac Corporation (you may have heard of the term FICO) and they take into consideration all of an individual’s debts:  credit cards, loans, bills.  These debts can range from your local utility company, cellular provider, medical collections, student loans, car payments, and sometimes rental history.  (Yes, landlords are now beginning to report the rent payments!)   


All of these credits are tallied and combined into a single, solitary number that is used to represent the individual’s risk, or in a positive light, the odds of the creditor receiving payment.   A credit rating of 720 seems to be the industry standard, the “gold” bar with which all ratings are judged.  Above 720, people can achieve lower rates and better loan terms.  Below it, well, it can sometimes feel like an uphill battle!

There are three companies that produce your FICO score or more commonly known as credit rating:  TransUnion , Experian, and Equifax.  Several factors come into play in determining this number.  However, three factors stand out above the rest.  Let’s take a look at those…

1.       PAYMENT HISTORY:  This one probably holds the top spot in accountability.  (sorry for the pun!)  How long and how consistent (or inconsistent) payments were made are very important criteria.  If payments have been missed, TRY TO GET CURRENT!  Also, the more recent activity weighs more heavily.  With that being said, it will be more helpful to get current on the most recent debt, versus something from a few years ago.  However, the ultimate goal is to be current on all payments!

2.       ACCOUNT BALANCES TO CREDIT LIMITS:  This aspect looks at the ratio between the total debt against the total amount the creditors could possibly lend.  Lenders like to see two things in this category:  A.  long term credit history, and B.  a low usage ratio between the debt and maximum credit limits.  An often seen mistake is occurs when a credit card gets paid off and the account is then closed.  Once closed, that line of credit is eliminated, thus reducing the overall amount of potential credit available and this subtracts significantly from one helpful aspect of the ratio criteria.  Pay off the card, but keep the line of credit open (unless the card has an annual fee).

3.       LENGTH OF CREDIT HISTORY:  This one is easy…have credit…and do not close out the account!  It helps your overall credit score to have a documented long term historical account.  This will work to your benefit ESPECIALLY if the account is current, too.  If the account is not current, diligently work to get current on the payments and then take heed to #2!

HOW TO STRENGTHEN YOUR CREDIT SCORE


The goal now is to raise your credit score so you cannot be denied of the things you need or want.  The best way to do this is to work with a lender.  With a higher score, you can take advantage of better terms and lower interest rates which will save money throughout the course of the loan.   If your score is low and help is needed because dreams of purchasing a home are just that:  a dream, far from reality, there are programs and people that are willing to help you get your finances in order.  One of these individuals can be as simple as a phone call or a few mouse clicks away…and the door to open this avenue is actually in my office!   

The sequence of events to becoming qualified for a loan begins with simply contacting the mortgage department and applying online.  Dan Crance, Senior Loan Officer of Shelter Mortgage Company (www.DanCrance.com) can assist in this process.   If you do not qualify for a loan, Shelter Mortgage can make arrangements for a third party to work with the applicant to “clean-up” their finances and put them in a stronger financial position with an improved credit rating.  Depending on the applicant, the process times can vary (normally it’s just a few months) and there are fees involved.  However, once the process is completed, you will be referred back to Shelter Mortgage and your referring real estate agent (for instance, myself!) will be notified.   At that point, the door to home ownership is open for you to walk through!

Ultimately, you are in total control of your credit score.  Remember, YOUR score is calculated by other individuals and when people get involved, mistakes can happen...sometimes often.  You should check your credit score on an annual basis just to make sure that it is accurate and you are not being penalized for false transactions.   Go to https://www.annualcreditreport.com/cra/index.jsp  to get a FREE copy of your report.  If you see any discrepancies, now would be the time to have them corrected and they are easy to fix!   Also, if you plan on obtaining financing for a home purchase, it is a good idea to review your credit report BEFORE you find your dream home.  If it turns out there are issues that may prevent you from receiving the needed financing, it would hurt twice as much to find your home and know that you could be months away from purchasing it…and when you are finally in the position to buy, it might have already been sold!  Don’t let this happen to you.  Work on your credit today because your dream home, be it a rental OR a purchase, might just present itself tomorrow.

Contact me, Bo Turocy of Carolina One Real Estate, today  for more information or for helping you with any of your real estate needs!

Sincerely,

Bo Turocy
Broker Associate, Carolina One Real Estate

Click HERE to go to my Facebook page!

When not helping people with real estate decisions, click HERE! to see what Bo does in his spare time.

Monday, July 8, 2013

The Future Health and Wealth of the Charleston Area Real Estate Market


Our local market has changed and continues to change…for the better!  Below is a portion of a letter written by the president of Carolina One Real Estate, Michael Scarafile, that was just recently published in the Charleston News and Courier.


"June 23, 2013

To Carolina One Real Estate Clients and Friends,

It is certainly amazing how fast the real estate market can change. As we approach the halfway point of 2013, I wanted to take a minute to update you on the Metro Charleston real estate market, to let you know where we are now, and what that might mean for you.

                                                                  The Facts

The overall real estate market is strong. Compared to this time last year, the number of homes for sale is down 13%. Written contracts have increased 27% and closed sales have increased 22%. A “healthy” market is driven by a balance between supply and demand. As demand for housing increases and supply diminishes, values increase. In the Charleston Trident Association of Realtors MLS, the average sales price, compared to this time last year, has increased 5.6% and the median price has increased 8.1%. All good news.

                                    If I want to buy, what does this mean for me?

Real Estate continues to be extremely affordable. It is important to understand the difference between the “price” and the “cost” of buying a home. For example, if you bought a $200,000 home with a 10% down payment in 2006, the top of the market, with average interest rates at 6.5% then, your monthly principle and interest payment would have been $1,137. Today, with average rates around 4%, a $200,000 home with a 10% down payment would cost $859 a month - 25% less!

Although prices and interest rates are beginning to edge up, both remain a real advantage to buyers right now. First time home buyers are often surprised to discover it can be more affordable today to buy than to rent and that they can qualify for a loan with several low down payment mortgage options available. And for move-up buyers, this is a unique window to be able to sell as the market is strengthening and at the same time buy while the rates are still low and good values are still available.

                                   If I want to sell, what does it mean for me?

The great news is that with fewer homes for sale and more buyers in the market, you have less competition, and most homes will sell for a higher price than in the last few years. There are many homeowners who wanted to sell several years ago and couldn’t, either because their mortgage was higher than the value in their home, or they chose not to because the timing was not right. If you fall into either category and are still thinking about moving, this is a good time to reevaluate.

                                          How can my Realtor help me?

Medicine is a great analogy. There’s more medical information on the Internet than we could ever use, but information is only a starting point. We still look to a doctor to use his/her training, knowledge and experience to diagnose and treat us as a unique individual. Real estate is no different. Your Realtor has the market knowledge and professional expertise to advise and guide you through the process in order to achieve your individual goals.

At Carolina One, we take our responsibility and commitment to you very seriously. We understand
the financial importance and emotional significance of buying or selling a home and are privileged to represent almost 1 of every 3 real estate buyers and sellers in Greater Charleston. If you’re thinking about buying or selling, want information specific to your situation or just have a question, it’s always our pleasure to help. Contact your Carolina One agent or email me personally and I’ll put you in touch with one of our professionals in your area.

On behalf of Carolina One and each of our sales associates, thank you for the opportunity to help.
Sincerely,

Michael Scarafile
President, Carolina One Real Estate"


I know that in the past few years quite a few individuals fell into the category of “accidental landlords”.  They had to rent their homes because the option of selling was not feasible due to the fallen appraised values of most homes in general.  But, as I mentioned earlier and was reinforced by Michael Scarafile, the market IS improving!

I’ve posted below a statistics spreadsheet of the local MLS areas for the first two weeks of June.  One of the most important facts that it illustrates is that the current inventory levels are decreasing…which means that there are fewer and fewer available homes on the market!

June 1-15, 2013 Charleston area MLS stats.


Lately, I have been working with renters searching for homes and I have noticed that the current rental inventory has decreased while the monthly rents have increased.  The good rental homes, like those on the sales market, do not last long!

I know that A LOT of people rent because they fear the large initial down payment required when purchasing a house.  It is great to know that there are special loan programs available to lessen that burden. 

If you would like to learn more about the local market and specifically to learn more to determine if now TRULY IS the right time to begin looking at investing in your own home, please contact me.  I can provide you with more information to help you make the smartest decision for yourself and your family.


Also, on the other side of the home owning spectrum, if you already own a home and have contemplated selling in order to move into a more practical and accomodating home for your current lifestyle, or would for any of the many other various reasons, now might be the right time to sell.  If you would like to learn more about the local market and specifically how it applies to your local investment…your home…please let me know.  I’d be more than happy to research it for you and help you determine if the right time to sell TRULY IS now!

Call or email me today for more information!


Bo Turocy Carolina One Real Estate Facebook Page

Email me (click here)  or call 843.974.6200